
OBORDA / AVIATION INFRASTRUCTURE
AT&T is a large telecommunications operator. An FAA network award fits its enterprise connectivity business, but wireless, fiber, capital spending and debt remain much larger drivers of the stock.
Observe: what is confirmed?
USAspending records a $74.3 million FAA Enterprise Network Services early-start development and planning order beginning August 12, 2026. This is a funded entry point; it does not establish that AT&T receives an assumed multibillion-dollar share of the new request.
Sources: USAspending: AT&T FENS funded task orderEarnings and valuation
Q3 guidance calls for adjusted EPS around $2.40 and 2026 free cash flow of at least $18 billion. I use $2.40 as an earnings anchor. Capital investment remains substantial, and debt reduction is important.
Sources: AT&T: Q3 2026 resultsPrice structure
The $22.18 November 13 reference price is 24.66% below the $29.44 52-week high in the selected price series. High and indicator values differ across dividend-adjusted vendors; use one consistent series for execution.
Sources: AT&T price and 52-week rangeOrient: how the FAA story fits
AT&T deserves a place in the communications workstream. Its confirmed startup order is a more current basis for discussion than simply repeating Verizon’s original 2023 FENS announcement. Even so, FAA upside is likely diluted at the parent-company level.
Timing: Initial planning order: August 2026–August 2027 recorded period. Further network rollout: 2027–2029 analytical window, conditional on funded scope, execution and network transition decisions.
Business-to-stock bridge: Funding must become an obligation, an awarded scope of work, profitable delivery and ultimately cash flow. I have not assigned this company an invented share of the proposed $50 billion.
Decide: six valuation zones
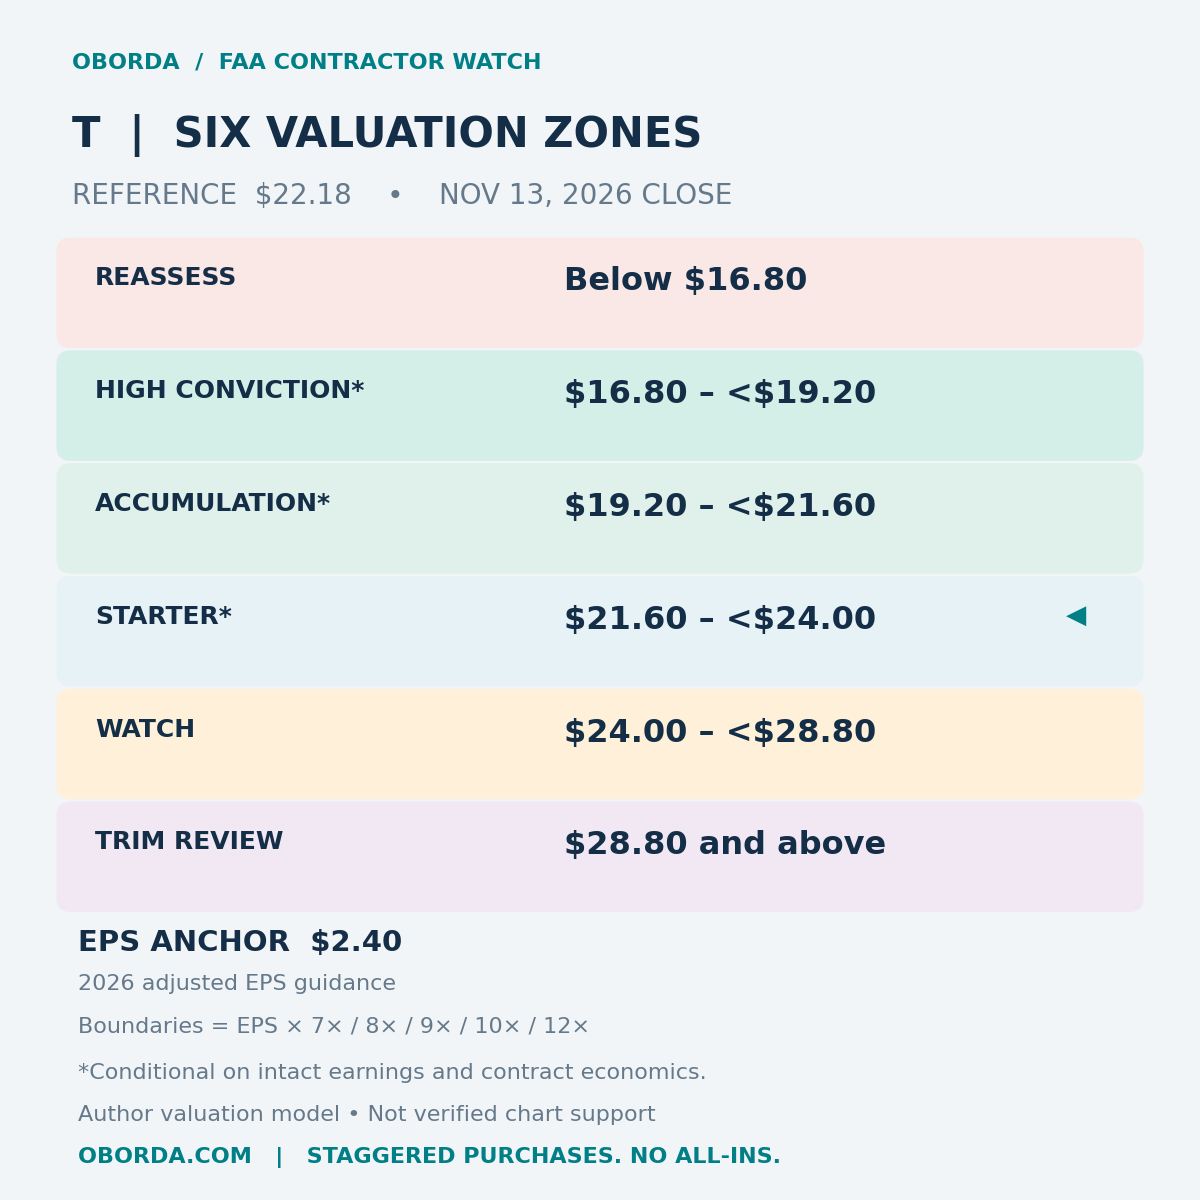
Anchor: $2.40 annual EPS; snapshot multiple: 9.24×. Boundaries equal EPS × the stated multiple. These are provisional valuation bands, not verified chart support. Multiples are my risk allowances, not peer-consensus targets. They deliberately exclude an assumed incremental FAA earnings contribution.
| Zone | Price | Boundary rationale |
|---|---|---|
| Reassess | Below $16.80 | Below 7× EPS: the price may signal a broken assumption; stop and re-underwrite. |
| High conviction — conditional | $16.80 to below $19.20 | 7–8×: deepest valuation allowance, conditional on intact earnings and contracts. |
| Accumulation — conditional | $19.20 to below $21.60 | 8–9×: larger margin of safety; stagger entries. |
| Starter — conditional | $21.60 to below $24.00 | 9–10×: smaller initial position; no presumed FAA windfall. |
| Watch / no new money | $24.00 to below $28.80 | 10–12×: insufficient discount under this model. |
| Trim review | $28.80 and above | At least 12×: review concentration and valuation; no automatic sale. |
The lowest bands permit more valuation risk only while business quality remains intact. A falling price after adverse contract news is a reason to reassess, even inside a buy band. These stocks share federal-spending exposure, so buying several is not full diversification.
12–24 month valuation scenarios
Bear: EPS falls 15% and valuation contracts to the lowest modeled multiple. Base: EPS holds and trades at the midpoint of the starter multiples. Bull: EPS grows 10% and trades at the trim-review multiple. These are conditional sensitivities, not probability-weighted expected returns. Price returns exclude dividends, taxes and fees.
| Case | EPS assumption | P/E | Implied price | Return vs reference |
|---|---|---|---|---|
| Bear | $2.04 | 7× | $14.28 | -35.6% |
| Base | $2.40 | 9.5× | $22.80 | +2.8% |
| Bull | $2.64 | 12× | $31.68 | +42.8% |
Risks and invalidation
Large capital requirements, leverage, enterprise pricing pressure and legacy copper costs. Parent-company cash flow may matter more than federal headline wins.
Thesis breaks if: Deteriorating free cash flow, weaker debt-reduction capacity or unfavorable network-contract economics would invalidate an income-and-value entry thesis.
Confidence: High on the recorded initial order; medium on parent valuation; low on incremental FAA earnings materiality.
Act: my next move
Conditional small starter at $22.18 on the broader AT&T cash-flow thesis. The FAA opportunity alone is insufficient reason to buy.
Next evidence to check: funded task orders, award modifications, company backlog commentary, margins and cash collections. Price bands are review points, not standing orders. Staggered purchases. No all-ins.
Market context and limits
Federal procurement can proceed while the wider market falls. Higher discount rates would reduce the multiples I am willing to pay. I assign no seasonal November/December return advantage: the catalysts here are appropriations, awards and results. Current options positioning, institutional flows and a fully reconciled adjusted OHLC history were not verified; no flow claim or automated technical signal is used. The missing data limits confidence in entry timing. Refresh prices, corporate actions and earnings guidance before acting.
OODA: Observe the funded scope → Orient it against the whole company → Decide whether valuation compensates for risk → Act only when both evidence and price qualify.