
OBORDA / AVIATION INFRASTRUCTURE
SAIC provides government technology, engineering and mission services. It is a separate publicly traded company from Leidos, despite their shared corporate history.
Observe: what is confirmed?
SAIC reported $100 million of FAA task orders after its first FY2027 quarter, covering systems engineering, software development and related support. Those are existing awards, not proof of an allocation from the proposed $50 billion.
Sources: SAIC: Q1 FY2027 results and FAA ordersEarnings and valuation
Its August 31 outlook put FY2027 adjusted EPS at $10.65–$10.75; I use $10.70. Quarterly book-to-bill was 0.6 and trailing-twelve-month book-to-bill 0.8, which merits attention despite the FAA orders.
Sources: SAIC: Q2 FY2027 resultsPrice structure
The November 13 close of $150.24 is only 3.14% below the $155.11 52-week high. That offers a smaller high-to-price discount than most names in this group; it is a poor reason to chase an infrastructure headline.
Sources: SAIC price and 52-week rangeOrient: how the FAA story fits
Engineering and testing can be needed across multiple workstreams. SAIC is smaller than RTX, so meaningful incremental awards could matter more proportionally, but weak aggregate bookings argue against assuming that one customer fixes the growth outlook.
Timing: Current orders: 2026 onward under their awarded terms. Additional engineering, testing and integration: 2027–2030 estimate, potentially alongside both hardware and software deployments.
Business-to-stock bridge: Funding must become an obligation, an awarded scope of work, profitable delivery and ultimately cash flow. I have not assigned this company an invented share of the proposed $50 billion.
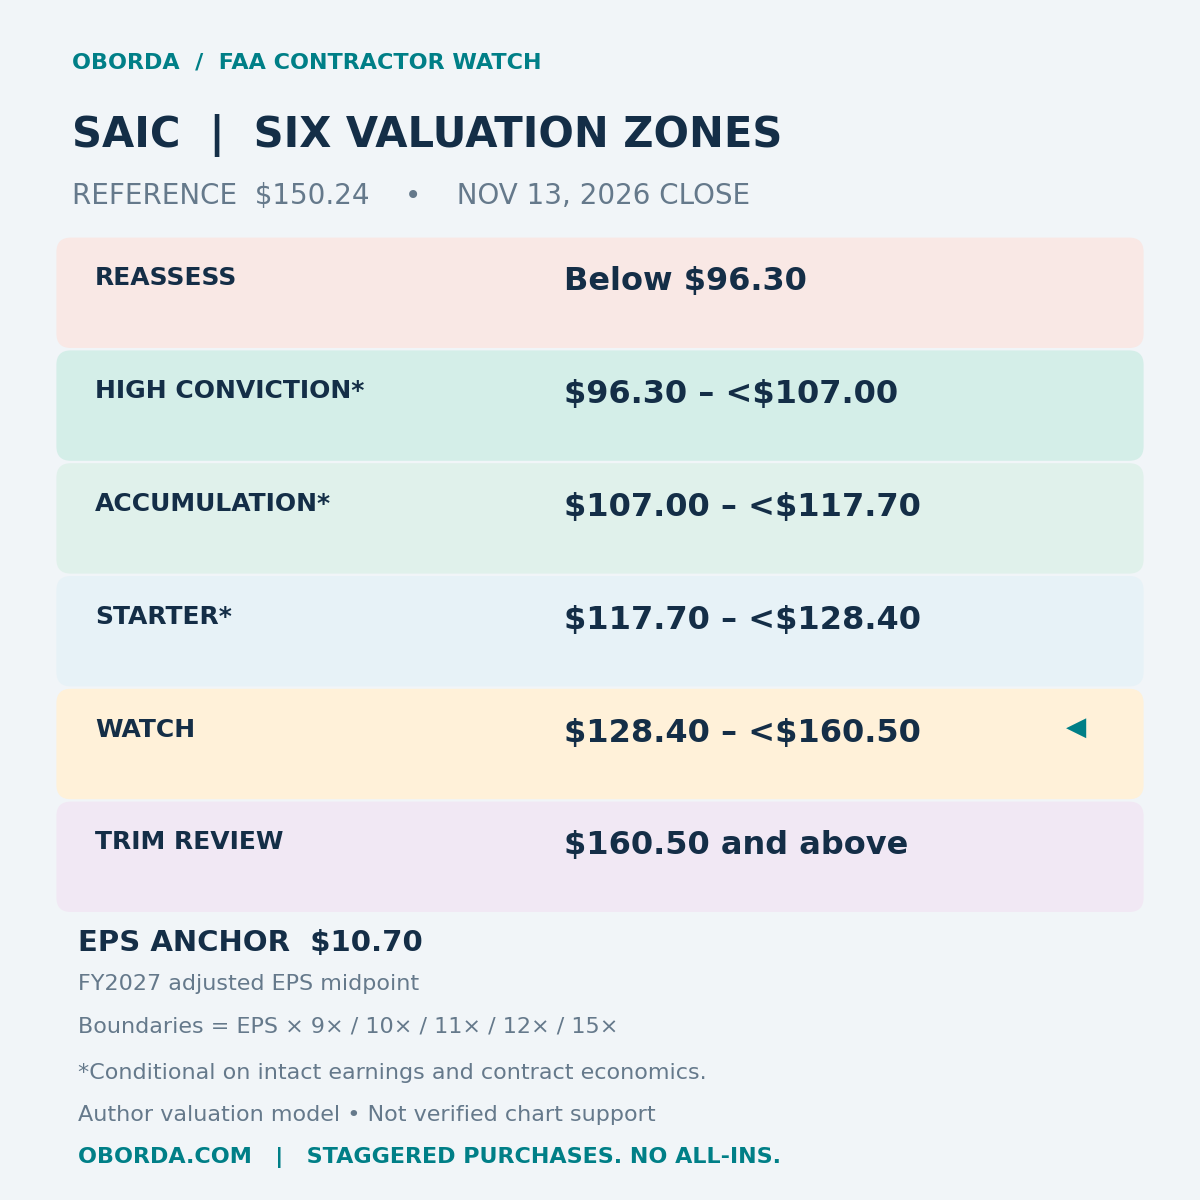
Decide: six valuation zones
Anchor: $10.70 annual EPS; snapshot multiple: 14.04×. Boundaries equal EPS × the stated multiple. These are provisional valuation bands, not verified chart support. Multiples are my risk allowances, not peer-consensus targets. They deliberately exclude an assumed incremental FAA earnings contribution.
| Zone | Price | Boundary rationale |
|---|---|---|
| Reassess | Below $96.30 | Below 9× EPS: the price may signal a broken assumption; stop and re-underwrite. |
| High conviction — conditional | $96.30 to below $107.00 | 9–10×: deepest valuation allowance, conditional on intact earnings and contracts. |
| Accumulation — conditional | $107.00 to below $117.70 | 10–11×: larger margin of safety; stagger entries. |
| Starter — conditional | $117.70 to below $128.40 | 11–12×: smaller initial position; no presumed FAA windfall. |
| Watch / no new money | $128.40 to below $160.50 | 12–15×: insufficient discount under this model. |
| Trim review | $160.50 and above | At least 15×: review concentration and valuation; no automatic sale. |
The lowest bands permit more valuation risk only while business quality remains intact. A falling price after adverse contract news is a reason to reassess, even inside a buy band. These stocks share federal-spending exposure, so buying several is not full diversification.
12–24 month valuation scenarios
Bear: EPS falls 15% and valuation contracts to the lowest modeled multiple. Base: EPS holds and trades at the midpoint of the starter multiples. Bull: EPS grows 10% and trades at the trim-review multiple. These are conditional sensitivities, not probability-weighted expected returns. Price returns exclude dividends, taxes and fees.
| Case | EPS assumption | P/E | Implied price | Return vs reference |
|---|---|---|---|---|
| Bear | $9.09 | 9× | $81.85 | -45.5% |
| Base | $10.70 | 11.5× | $123.05 | -18.1% |
| Bull | $11.77 | 15× | $176.55 | +17.5% |
Risks and invalidation
Weak bookings, recompete losses, staffing costs, financing costs and margin pressure. Government engineering demand does not automatically mean high incremental profit.
Thesis breaks if: Persistently weak book-to-bill, cuts to the earnings anchor or loss of meaningful FAA work would require a reassessment.
Confidence: High on disclosed FAA orders; medium on valuation inputs; low on the amount of new funding it could capture.
Act: my next move
Watch at $150.24. My starter band ends at $128.40. Require either a lower price or verified higher sustainable earnings before increasing the valuation allowance.
Next evidence to check: funded task orders, award modifications, company backlog commentary, margins and cash collections. Price bands are review points, not standing orders. Staggered purchases. No all-ins.
Market context and limits
Federal procurement can proceed while the wider market falls. Higher discount rates would reduce the multiples I am willing to pay. I assign no seasonal November/December return advantage: the catalysts here are appropriations, awards and results. Current options positioning, institutional flows and a fully reconciled adjusted OHLC history were not verified; no flow claim or automated technical signal is used. The missing data limits confidence in entry timing. Refresh prices, corporate actions and earnings guidance before acting.
OODA: Observe the funded scope → Orient it against the whole company → Decide whether valuation compensates for risk → Act only when both evidence and price qualify.