
OBORDA / AVIATION INFRASTRUCTURE
Indra Group is a Spanish technology and defense company with air-traffic-management operations. The relevant ordinary shares trade in Madrid as IDR. U.S. ticker IDR refers to a different company, Idaho Strategic Resources; a ticker-only U.S. search can lead to the wrong investment.
Observe: an actual award
Indra Group USA announced a $342 million FAA radar contract in January 2026, with production at a new Kansas City-area facility. This is an existing award under the modernization program, not an assumed slice of the proposed new $50 billion.
Sources: Indra: $342 million FAA radar awardThe FAA’s RTX/Indra program targets replacement of up to 612 radars by June 2028. That is a program-wide count, not Indra’s disclosed unit allocation. I would not divide it equally between suppliers.
Sources: FAA: RTX and Indra radar awards, January 5, 2026Financial evidence
Indra reported nine-month revenue growth of 29% and backlog of €22.165 billion. Air Traffic revenue grew 23%. Acquisitions contributed to group growth, so the headline expansion should not be treated as purely organic or FAA-driven.
Sources: Indra: nine-month 2026 resultsA historical Madrid price record shows a November 13 close of €58.80. It is a dated reference, not a November 16 live quote. A consistent 52-week series and sustainable diluted EPS anchor were not established in this review; I withhold the correction calculation and a current P/E rather than combine incompatible inputs.
Sources: Indra Madrid: historical prices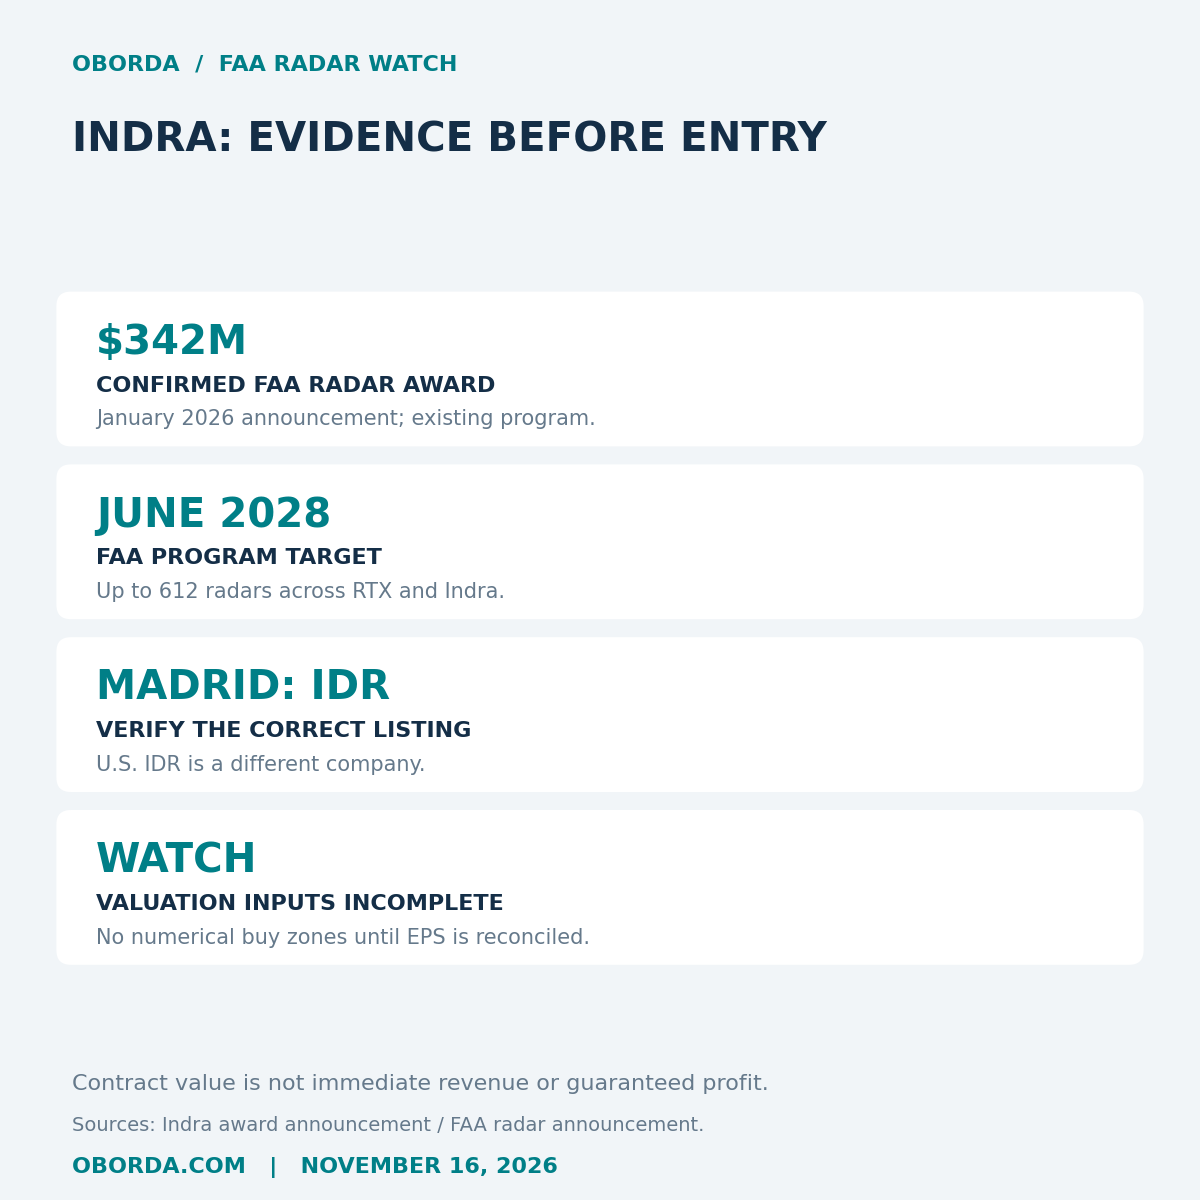
Orient: radar exposure with a different risk mix
Indra provides a direct way to examine the radar workstream, but the investment also depends on Spanish and European defense demand, acquisitions, governance, manufacturing capacity and currency. A dollar contract does not translate one-for-one into euro earnings. The U.S. manufacturing commitment creates both opportunity and delivery obligations.
Timing: production and installation are already part of the 2026–2028 radar cycle. Incremental awards after a new appropriation could arrive during 2027–2029; that is an analytical window, not an awarded schedule. Maintenance may extend beyond deployment if separately contracted.
Decide: keep the six-zone discipline
A numerical grid would imply more confidence than the verified valuation inputs support. Here are the evidence gates that must be satisfied before numerical zones are published.
| Zone | Required evidence |
|---|---|
| Reassess | Adverse award change, production failure or earnings impairment; suspend buying. |
| High conviction — conditional | Verified earnings, balance sheet and quote; a deep valuation discount with delivery intact. |
| Accumulation — conditional | Funded backlog and profitable execution, plus a substantial discount to independently modeled value. |
| Starter — conditional | Verified listing and earnings anchor, acceptable valuation and confirmed contract economics. |
| Watch / no new money | Current status: genuine FAA role, incomplete per-share valuation. |
| Trim review | Require a verified valuation above the justified range or excessive portfolio concentration. |
Upside and downside
The bullish path is successful U.S. radar delivery, additional funded orders and durable air-traffic margins. The bearish path is startup cost overruns, delivery delays or a valuation decline in the broader defense business. Numerical 12–24 month return scenarios are withheld until per-share inputs are reconciled; a confirmed contract alone cannot establish expected stock upside.
Act: watch and complete the valuation
Observe the award and manufacturing milestones → Orient against group-wide cash flow and currency → Decide only after verifying ordinary-share EPS and price history → Act with a staggered entry if valuation qualifies. No purchase recommendation at €58.80 is established here.
Invalidation: a material contract cancellation, unfavorable amendment or persistent production problems would weaken the FAA thesis. Confidence: high on the award, medium on delivery timing, low on stock-entry valuation. Options flows and current institutional positioning were not verified. No seasonal trade thesis is assumed.