
OBORDA / Investment Analysis / October 8, 2026
FOXA Stock Analysis: 6 Buy Zones After a 16.8% Correction
FOXA stock analysis starts with one question: Is a 16.8% decline a discount—or just a cheaper price?
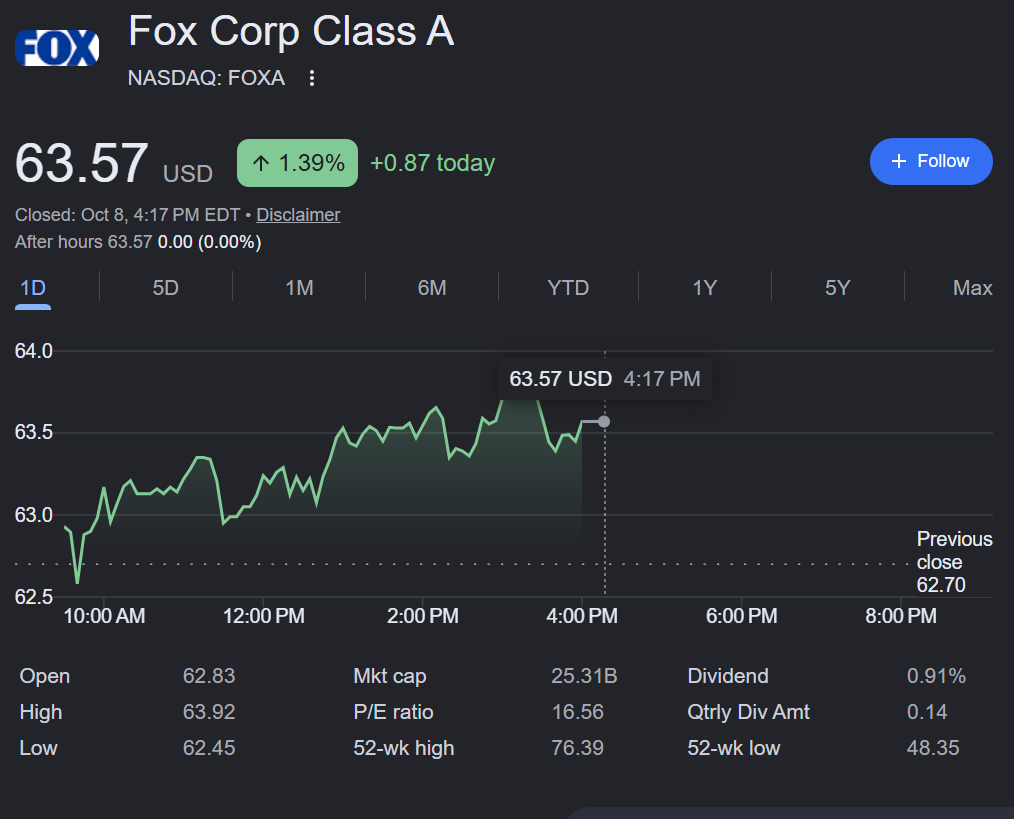
Fox Corporation ended October 8 at $63.57, below its 52-week high of $76.39. The market has marked the stock down, but I don’t buy a stock because the chart is red. I want the business, valuation and price structure to make sense together.
That’s the point of OBORDA: OBserve. ORient. Decide. Act. The goal isn’t to predict tomorrow’s tick. It’s to know what decision makes sense at different prices, and what would change that decision.
FOXA Stock Analysis: The Market Message
FOXA has bounced from an October 1 close near $61.28 to $63.57. That’s a useful improvement, but it’s not yet a proven breakout. October 8 volume was about 2.57 million shares, below a recent 50-day average near 5.1 million.
That tells me to watch the rebound rather than chase it. I want to see whether buyers can push through the $64–65 area and defend it. The broader market backdrop remains 🟡 mixed/rotational, so a single stronger session does not settle the trend.
FOXA Stock Buy Zones: Where Risk/Reward Changes
These six zones are conditional decision ranges, not predictions or guaranteed support. They combine observed chart levels with valuation based on Fox’s fiscal 2026 adjusted earnings. The lower ranges require fresh fundamental confirmation.
| OODA zone | Price | Decision |
|---|---|---|
| 🔴 No New Buys / Trim | Above $75 | Review extension and position size |
| 🟡 Watch | $65–75 | No chasing |
| 🟢 Starter — current | $61–65 | Small initial exposure only |
| 🟢🟢 Accumulation | $56–61 | Better value if thesis holds |
| 🔥 High Conviction Candidate | $51–56 | Recheck earnings and transaction risk |
| ⚡ Exceptional / Reassess | Below $51 | Investigate why the stock fell |
My preferred area for additional new capital is $56–61—not because an arbitrary percentage says so, but because that range represents a deeper discount to reported adjusted earnings. A weakening earnings outlook can invalidate even that zone.
What the FOXA Fundamentals Are Telling Me
For fiscal 2026, Fox reported $17.13 billion in revenue (+5%), $3.91 billion in adjusted EBITDA (+8%) and $5.42 adjusted EPS (+13%). GAAP EPS, however, was $3.84 (down roughly 22%). That’s not a detail to bury: stronger adjusted performance and weaker reported earnings deserve separate scrutiny.
| FY2026 | Result | YoY |
|---|---|---|
| Revenue | $17.13B | +5% |
| Adjusted EBITDA | $3.91B | +8% |
| Adjusted EPS | $5.42 | +13% |
| GAAP EPS | $3.84 | −22% |
Fox News and live sports remain important advertising and distribution franchises. Tubi and FOX One give the company routes into digital viewing. But cord-cutting, sports-rights costs, streaming economics and the announced Roku transaction add meaningful questions about how much of that growth becomes durable free cash flow.
FOXA Valuation: A Discount Needs a Reason
At $63.57, FOXA trades at approximately 11.7× FY2026 adjusted EPS and 16.6× FY2026 GAAP EPS. These are based on reported fiscal-year earnings, not an updated forward consensus.
| Adjusted EPS multiple | Illustrative share value |
|---|---|
| 10× | $54.20 |
| 11× | $59.62 |
| 12× | $65.04 |
| 13× | $70.46 |
| 14× | $75.88 |
This is why I distinguish a starter at $61–65 from accumulation at $56–61. The former is about 11.3–12× adjusted earnings; the latter is about 10.3–11.3×. Around $51–56, the implied multiple gets closer to 9.4–10.3×, but lower prices may reflect legitimate deterioration. These figures are valuation sensitivities, not price targets.
Technical Levels: What Would Confirm—or Break—the Setup?
$60–61 is the recent support area. $64–65 is near-term resistance, with $67–69 a higher overhead trading region. Above that sits the $75–76.39 area near the prior high.
A sustained move above $65 on stronger volume would add confidence. A decisive break below $60, especially with weaker guidance, would shift the task from buying to reassessing. The $56–59 and $51–55 levels are primarily valuation scenarios; independently verified chart support is not established there.
What Could Go Right—and What Could Go Wrong?
Catalysts: Tubi advertising monetization, FOX One adoption, sports/news advertising resilience, buybacks and potential Roku-related benefits.
Risks: Cable subscriber losses, rising sports costs, ad-market weakness, the gap between adjusted and GAAP results, and Roku deal financing/integration uncertainty.
I also want updated guidance and a clearer free-cash-flow picture before calling any deep decline a high-conviction opportunity.
OODA: Observe. Orient. Decide. Act.
Observe: FOXA has fallen 16.78% from its high. The latest bounce is constructive but not a confirmed breakout. Revenue and adjusted operating earnings have grown.
Orient: The valuation is less demanding than at the high, while the underlying media business is changing. Digital growth does not erase structural cable and execution risks.
Decide: At $63.57, FOXA supports a selective starter, not aggressive accumulation. The more compelling new-money setup is $56–61 with fundamentals intact.
Act: Monitor $60 support, $65 resistance, next earnings, and any changes to the Roku thesis. If already invested, judge whether the original investment thesis and position sizing still justify holding. Do not average down just because the stock is cheaper.
My FOXA Stock Analysis Verdict
HOLD / SELECTIVE STARTER. Confidence: Moderate. The reported business performance, lower multiple and recent support area are encouraging. Forward free cash flow, acquisition risk and unverified longer-term technicals limit conviction.
FOXA is worth watching. But a correction is a reason to investigate—not permission to stop asking questions.
Cash is a position. Don’t buy the dip. Buy the discount.
Sources and Method
- Fox fiscal 2026 earnings release (SEC)
- FOXA historical prices and volume
- Fox Corporation corporate updates
Data snapshot: October 8, 2026 after the US market close. Prices are not live. Valuation ranges use historical adjusted EPS; other risks may change the assessment. This is a research framework, not a guarantee of returns.